BUSINESS LOAN
How to Choose the Best Location for Your Business
Choosing the best location for your business can have a major impact on visibility, customer...
Learn More

 October 12, 2026
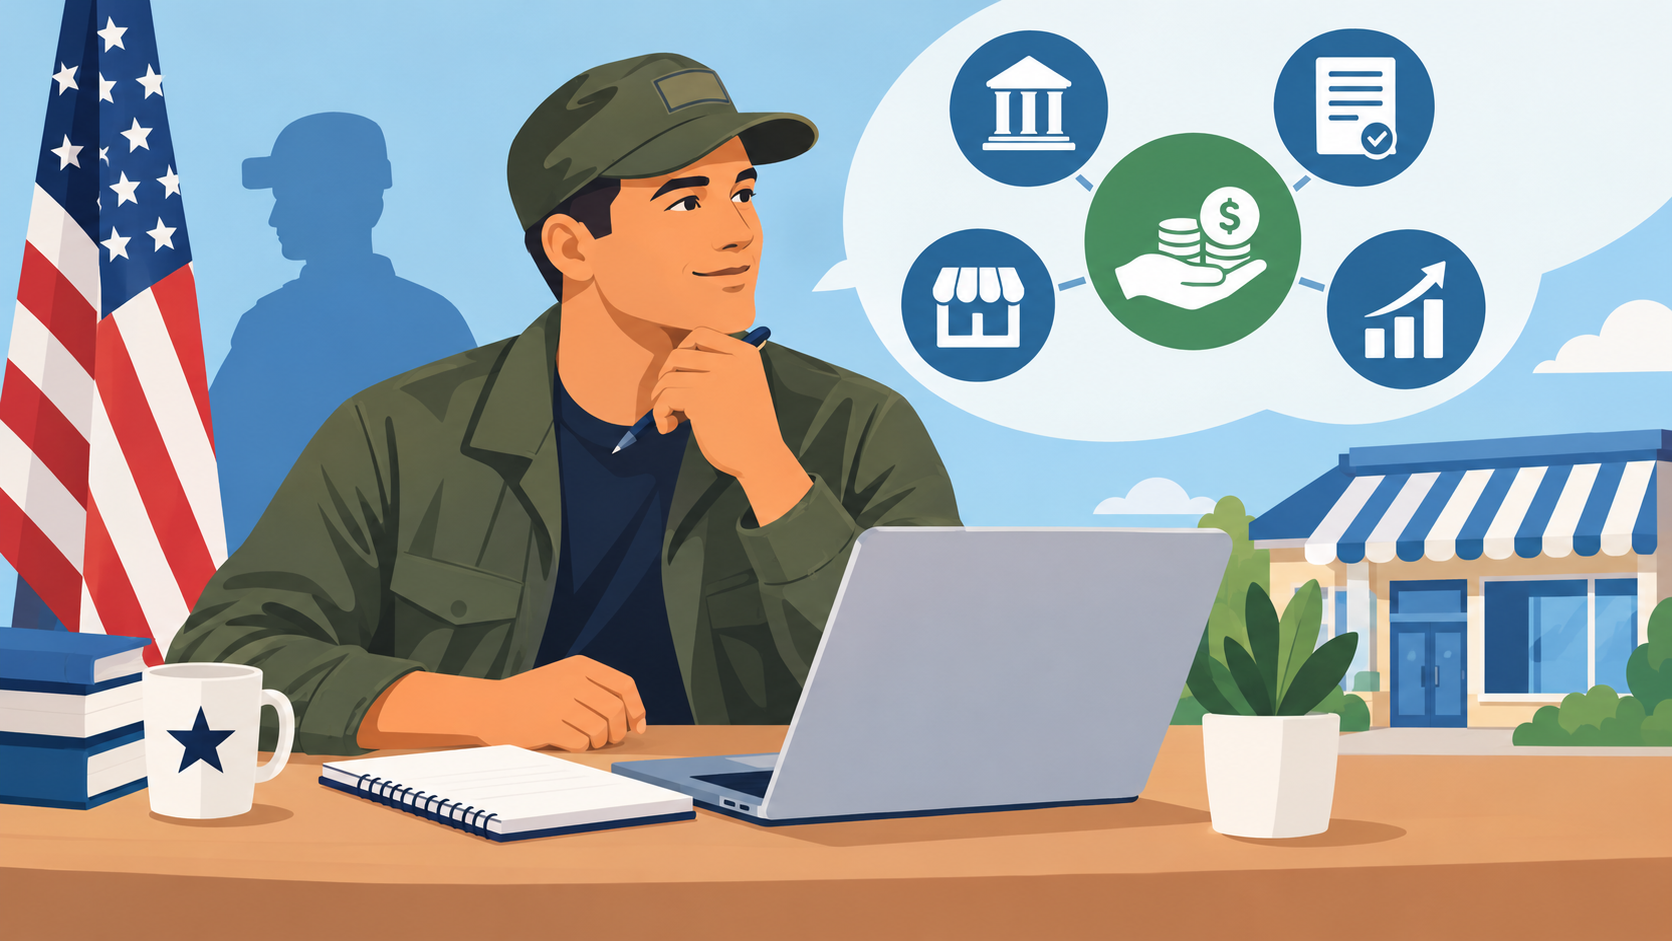
Starting a business after military service can be an exciting way to build financial independence and turn valuable skills into a long-term career. However, covering startup costs, purchasing equipment, hiring employees, and managing everyday expenses can be challenging without enough capital. Small business loans for veterans can help bridge that gap.
Veteran entrepreneurs have access to several financing options, including U.S. Small Business Administration (SBA) loan programs, conventional business loans, and specialized funding for eligible military reservists. Although there is no single loan that fits every business, understanding the available programs can help you choose financing that matches your goals, budget, and repayment capacity.
This guide explains how veterans’ business loans work, the main SBA financing options, eligibility requirements, application steps, and practical ways to prepare your business for funding.
A small business loan for veterans is financing that helps eligible military veterans fund business-related expenses. Depending on the lender and loan program, the money may be used to launch a startup, purchase inventory, acquire equipment, hire employees, manage cash flow, or expand an existing company.
Like other business loans, most require repayment of the borrowed principal plus interest and any applicable fees. The repayment period, interest rate, collateral requirements, and approval criteria depend on the specific financing arrangement.
The U.S. Small Business Administration does not generally lend money directly to businesses through its standard 7(a) and 504 loan programs. Instead, it provides guarantees to participating lenders, helping eligible small businesses access financing. The lender still reviews the application and makes the lending decision.
Veterans may also qualify for certain fee reductions, business training, and entrepreneurial support programs. These benefits depend on the specific program, current SBA rules, and the applicant’s eligibility.
For aspiring entrepreneurs, researching small business ideas for military veterans can be a useful first step before deciding how much capital to borrow.
Veterans can explore several financing programs, but three options deserve particular attention: SBA Express loans, SBA 7(a) loans, and Military Reservist Economic Injury Disaster Loans (MREIDL).
Each program serves a different purpose, so it is important to understand how its funding limits, eligibility requirements, and permitted uses compare.
SBA Express is part of the SBA’s 7(a) loan program and is designed to provide a streamlined application process for eligible small businesses. Participating lenders generally have greater authority to make decisions on Express applications, which can help simplify the lending process.
The program is available to qualifying businesses regardless of whether the owner is a veteran. However, eligible veteran-owned businesses may benefit from applicable SBA fee relief or other support available under current program rules.
SBA Express financing can help businesses cover working capital, purchase equipment, acquire inventory, or meet other eligible business expenses. Depending on the loan structure, funds may also support certain business acquisition or refinancing needs.
The maximum SBA Express loan amount is generally $500,000 under current program rules. The SBA’s guarantee to the lender is generally lower than the guarantee available under the standard 7(a) program, and approval is not automatic.
When it may be useful: An established veteran-owned business that needs financing for equipment, inventory, or working capital may consider SBA Express if the amount and repayment terms fit its needs.
Before applying, compare interest rates, lender fees, collateral requirements, and repayment schedules. A faster application process does not necessarily mean a lower borrowing cost or guaranteed approval.
The SBA 7(a) loan program is one of the agency’s primary financing options for small businesses. It can support a wide range of eligible business activities, making it useful for both established companies and qualified entrepreneurs preparing to launch a business.
Eligible borrowers may be able to use 7(a) financing for:
Starting or acquiring an eligible business.
Purchasing equipment, machinery, or inventory.
Funding working capital and ordinary operating expenses.
Buying or improving eligible commercial real estate.
Refinancing certain qualifying business debts.
Expanding operations or purchasing an existing business.
The maximum loan amount under the standard 7(a) program is generally $5 million. Actual loan amounts depend on the business’s financing needs, eligibility, repayment ability, and lender assessment.
Veterans should also investigate whether they qualify for SBA fee relief. Certain eligible veteran-owned businesses may receive relief from the upfront SBA guaranty fee on qualifying loans under applicable program rules. The amount of any benefit depends on the loan and the rules in effect when the application is processed.
When it may be useful: A veteran purchasing an existing company, opening a larger operation, or seeking substantial working capital may find the 7(a) program worth exploring.
Because these loans can involve significant financial commitments, prepare realistic revenue projections and a clear explanation of how the business will generate enough cash to make its payments.
The Military Reservist Economic Injury Disaster Loan program is intended to help eligible small businesses recover when an essential employee is called to active military duty.
Unlike general-purpose business loans, MREIDL financing addresses a specific problem: the financial injury a business experiences because an essential employee is unavailable due to qualifying military service.
For example, a small company may rely on a reservist who manages daily operations, oversees production, or handles a critical technical role. If that employee is called to active duty, the business may face additional expenses or reduced revenue while trying to maintain operations.
An eligible business may use MREIDL funds for necessary operating expenses that it could have met under normal circumstances but cannot cover because of the economic injury caused by the employee’s military service.
The maximum loan amount is generally $2 million, but the SBA determines the approved amount based on the business’s actual economic injury and repayment ability. Not every applicant will qualify for the maximum.
MREIDL proceeds have important restrictions. They generally cannot be used to expand the business, replace lost profits, refinance long-term debt, or pay obligations that the business could have met without the economic injury.
When it may be useful: A qualifying small business facing financial disruption because an essential reservist employee has been called to active duty may consider this specialized program.
Business owners should review the SBA’s current eligibility criteria, documentation requirements, and permitted uses before applying.
The term VA business loan can be confusing because it may suggest that the U.S. Department of Veterans Affairs offers a general-purpose business loan program similar to its home loan benefits.
In practice, veterans usually seek business financing through SBA-backed loans, banks, credit unions, online lenders, or other commercial financing providers. The VA is not generally the direct provider of standard small business loans for veterans.
SBA programs are available to qualifying businesses based on their program requirements, not exclusively to veteran owners. Veteran status may provide access to particular benefits, fee relief, or specialized support, but it does not eliminate normal lending requirements.
Other financing options may include conventional bank loans, business lines of credit, equipment financing, and eligible grants or local economic development programs.
Understanding these distinctions helps veterans avoid misleading offers and focus on legitimate funding sources that match their business plans.
Eligibility depends on the loan program and lender. Although some programs offer benefits to veterans, most SBA-backed business loans require the business to meet standard financial, operational, and ownership criteria.
Common factors include the following.
Some veteran-focused resources and benefits require applicants to provide documentation of their military service. Depending on the program, acceptable documents may include a DD Form 214 or other official military records.
Veteran status alone does not guarantee loan approval. The lender may also review ownership percentages, the business structure, and whether the company meets the applicable SBA requirements.
Lenders commonly review personal credit histories and, when available, business credit reports. These help them assess how the applicant has managed previous financial obligations.
A lower credit score does not automatically mean every financing option is unavailable, but it may limit the number of lenders willing to approve an application or affect the offered terms.
For established businesses, lenders often examine financial statements, tax returns, revenue history, and existing debt. Startups may need detailed financial projections because they do not yet have an operating track record.
The central question is whether the business can reasonably repay the loan while continuing to cover its operating expenses.
Standard SBA 7(a) loans generally require the business to operate for profit in the United States, meet SBA size standards, and avoid excluded business categories.
Eligibility can vary for specialized programs, so applicants should confirm the requirements for the particular loan they intend to pursue.
Preparing a loan application takes time, but an organized approach can help you compare options and avoid unnecessary delays.
Start by calculating how much money you actually need. Separate one-time startup expenses from recurring costs such as rent, payroll, insurance, utilities, and inventory.
For example, an entrepreneur opening a small service business might need funds for equipment, licensing, marketing, and several months of working capital. Listing these costs individually creates a clearer picture of the total financing requirement.
Avoid borrowing more than necessary simply because a lender offers a larger amount.
Match the loan to your intended use.
An SBA 7(a) loan may suit a business acquisition or a broader financing requirement. SBA Express may be worth exploring when you need a smaller loan with a streamlined application process. MREIDL is designed for qualifying economic injuries caused by an essential reservist employee’s call to active duty.
You can review the SBA’s official business loan programs to understand available financing and identify participating lenders.
A business plan should explain what your company does, who its customers are, how it will generate revenue, and why it can succeed in its market.
Include a realistic description of your products or services, competitors, pricing, marketing strategy, operating expenses, and expected cash flow.
If you are applying for startup financing, financial projections are particularly important. Show how you estimated sales and expenses, and explain what you will do if revenue grows more slowly than expected.
The exact documents vary by lender and program, but you may be asked to provide:
Government-issued identification and military service documentation, where applicable.
Business registration and ownership records.
A business plan and detailed funding request.
Personal and business tax returns, when available.
Profit-and-loss statements and balance sheets.
Bank statements and cash-flow projections.
A list of existing loans and other financial obligations.
Quotes or invoices for equipment, inventory, or other planned purchases.
Organizing these materials in advance can make the application process more efficient.
Contact banks, credit unions, and SBA-approved lenders to discuss your financing needs. You can also use the SBA’s Lender Match service to connect with participating lenders.
Compare more than the advertised interest rate. Review the annual percentage rate where available, origination fees, repayment term, collateral requirements, personal guarantees, and any prepayment conditions.
Ask how long the application and funding process typically takes. Processing times depend on the lender, the complexity of the request, and the completeness of your documentation.
Once you have selected a lender, submit the required documents and respond promptly to follow-up requests.
If approved, read the loan agreement carefully before signing. Confirm the approved amount, interest rate, payment schedule, fees, collateral arrangements, and any restrictions on how you can use the funds.
Do not commit to the loan until you understand the total cost and are comfortable with the repayment obligations.
SBA loans are not the only way to fund a business. Depending on your needs and qualifications, alternative financing may be worth considering.
Banks and credit unions offer business loans that are not backed by the SBA. These may suit established companies with strong financial records, reliable cash flow, and suitable collateral.
Terms vary by lender, so compare the total borrowing cost and qualification requirements before deciding.
A business line of credit allows an eligible company to borrow up to an approved limit and draw funds as needed. Interest is generally charged on the amount borrowed, according to the agreement.
This arrangement may help cover temporary cash-flow gaps, seasonal expenses, or unexpected operating costs. However, revolving credit can become expensive if balances remain outstanding or borrowing becomes a substitute for sustainable revenue.
Equipment financing can help businesses purchase machinery, vehicles, tools, or other qualifying assets. The equipment may serve as collateral, depending on the agreement.
This option can be useful when a specific purchase is necessary to begin operations or increase productivity. Compare the down payment, interest rate, repayment period, and any restrictions on the financed asset.
The SBA Microloan program provides smaller loans through approved intermediary organizations. These loans can be used for eligible working capital, inventory, supplies, furniture, and equipment.
The maximum microloan is generally $50,000. The intermediary determines its lending requirements and terms within SBA program rules.
Microloans may be worth considering for entrepreneurs who need modest startup funding rather than a larger commercial loan.
Some government agencies, nonprofit organizations, corporations, and local economic development groups offer grants, training, or business support for eligible entrepreneurs.
Unlike loans, grants generally do not require repayment when the recipient complies with the award conditions. However, grants are often competitive, limited to specific purposes, or restricted to certain applicants.
Be cautious of services that promise guaranteed grants in exchange for upfront fees. Verify opportunities through official government websites and established organizations before sharing sensitive financial information.
A strong application demonstrates that you understand your business, have a practical plan for using the money, and can manage the debt responsibly.
Keep your financial records organized. Make sure your tax filings, bank statements, business expenses, and revenue records are consistent and up to date.
Separate personal and business finances. A dedicated business bank account helps you track cash flow and present clearer financial information to lenders.
Reduce unnecessary debt. Review existing obligations and avoid taking on additional financing that could make monthly payments difficult to manage.
Build realistic financial projections. Base sales estimates on reasonable assumptions about demand, pricing, expenses, and operating capacity rather than best-case scenarios.
Explain how the loan will be used. Provide a clear breakdown of the requested amount and connect each expense to a specific business objective.
Seek professional guidance. SBA resource partners, including Small Business Development Centers and Veterans Business Outreach Centers, may offer counseling, business planning assistance, and help preparing for financing.
Finally, borrow with a repayment plan in mind. A loan should help the business reach a measurable goal without creating financial pressure that threatens its long-term stability.
Even promising businesses can encounter problems when their applications are incomplete or their financial plans are unrealistic.
One common mistake is choosing a loan based only on the maximum amount available. A larger loan is not necessarily better if the business does not need the funds or cannot comfortably afford the payments.
Another is overlooking fees and collateral requirements. An attractive interest rate may not reflect the full cost of financing, and some loans may require a personal guarantee or a security interest in business assets.
Applicants should also avoid submitting inconsistent information across financial statements, tax returns, and business plans. If figures differ, be prepared to explain why.
Finally, do not assume that military service automatically qualifies you for special financing or that every program accepts every veteran, spouse, or reservist. Check the official requirements before applying, particularly when a program has a specific eligibility purpose.
Small business loans can help eligible veterans start, acquire, operate, or expand a company.
SBA Express loans generally offer up to $500,000 through participating lenders, subject to approval.
SBA 7(a) loans generally provide up to $5 million for a wide range of eligible business purposes.
MREIDL financing supports eligible businesses affected when an essential reservist employee is called to active duty.
Veteran status may provide access to certain benefits and business support, but it does not guarantee loan approval.
Conventional loans, lines of credit, equipment financing, micro loans, and grants may provide alternatives.
A detailed business plan, organized financial records, and realistic repayment projections can strengthen an application.
Always compare the full cost, repayment terms, collateral requirements, and eligibility rules before accepting financing.
Veterans can apply for SBA-backed financing and other commercial loans if they meet the relevant requirements. Certain veteran-focused benefits, fee relief, training, and counseling may also be available, depending on the program and eligibility rules.
The standard SBA 7(a) program generally allows loans of up to $5 million, while SBA Express generally has a $500,000 maximum. MREIDL loans generally have a $2 million maximum, subject to program-specific rules and the business’s actual economic injury.
These limits are not guaranteed approval amounts. The lender or SBA determines eligibility and the amount that can be approved.
Possibly, depending on the loan amount, program, lender, and financial circumstances. Some SBA Express loans of $50,000 or less do not require collateral under SBA program rules, but lenders may still consider creditworthiness and repayment ability.
Larger loans may have collateral requirements, and applicants should confirm the terms directly with the lender.
It may be possible, but a low credit score can limit your options or affect the loan terms offered. Lenders may also consider business revenue, existing debt, payment history, available collateral, and the overall strength of your application.
Review your credit reports for errors, address outstanding obligations where possible, and prepare a realistic business plan before applying.
Eligible entrepreneurs may use certain SBA-backed loans to establish a business. However, startups must still satisfy program and lender requirements, which may include demonstrating repayment ability, providing financial projections, and contributing personal funds where required.
Approval depends on the specific loan, business model, and applicant’s circumstances.
Some grants and business development opportunities are available to eligible veterans, but there is no universal grant that automatically provides free startup money to every veteran. Eligibility, award amounts, application periods, and permitted uses vary.
Check official SBA resources, state and local economic development agencies, and established veteran business organizations for legitimate opportunities.
Military spouses can apply for many standard business financing programs if they meet the applicable requirements. However, a spouse does not automatically qualify for every veteran-specific benefit. Eligibility depends on the particular program, ownership structure, and other criteria.
Veterans can contact SBA resource partners, Small Business Development Centers, Veterans Business Outreach Centers, and participating lenders for guidance. These organizations may help with business planning, financial projections, funding research, and application preparation.
Small business loans can help veterans turn their experience, leadership, and professional skills into successful business ventures. The right financing depends on what the company needs, how much it can afford to repay, and which programs it qualifies for.
Start by defining your funding requirements, comparing SBA and non-SBA options, and preparing a clear business plan. With careful research and realistic financial planning, you can make a more informed decision about financing your next business venture.
How to Sell Business Internet Services to Small Businesses
Oct 23, 2026
Telecom Sales Call Quality Assurance: A Practical Guide
Oct 22, 2026
Telecom Dealer KPIs: Metrics That Drive Better Results
Oct 21, 2026
Telecom Sales Scripts That Help Turn Leads Into Sales
Oct 20, 2026
Telecom Lead Management: Follow Up Without Losing Sales
Oct 19, 2026

8
Oct, 2026
BUSINESS LOAN
Choosing the best location for your business can have a major impact on visibility, customer...
29
Sep, 2026
FINANCE
If you are thinking about applying for a personal or business loan, it is important...
22
Sep, 2026
FINANCE
Starting a business requires more than a good idea. You also need enough capital to...