FINANCE
How to Market Your Franchise and Attract More Customers
Marketing a franchise successfully requires more than simply promoting a brand. Franchise owners need a...
Learn More

 September 22, 2026
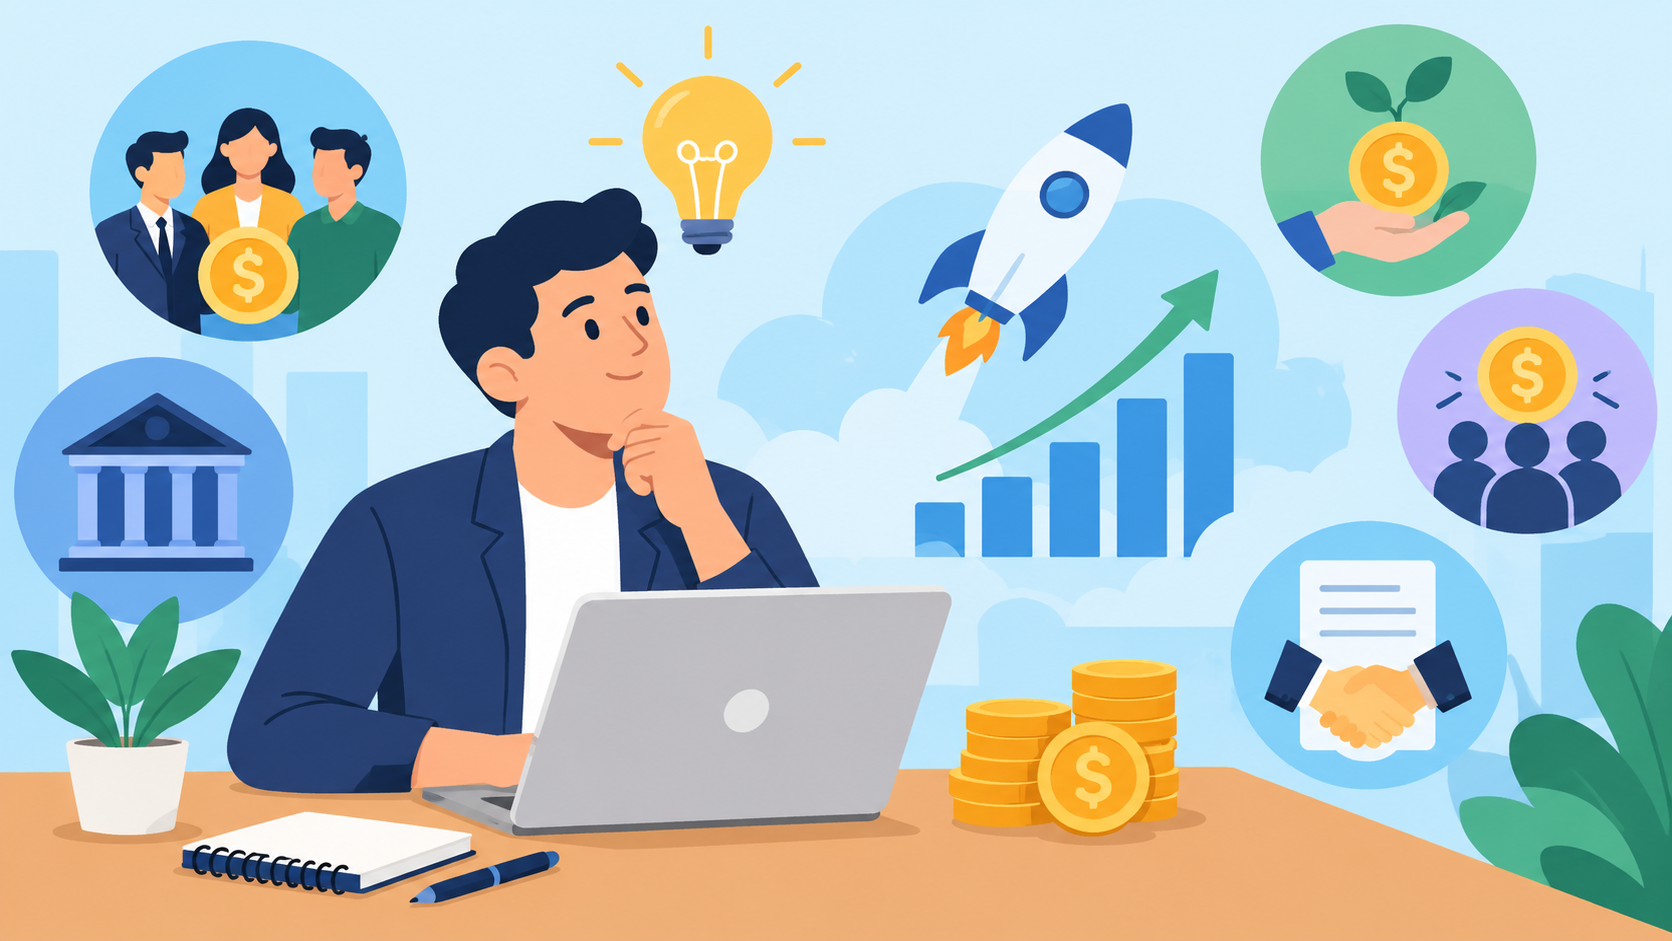
Starting a business requires more than a good idea. You also need enough capital to cover startup costs, operating expenses, equipment, inventory, marketing, and other early investments. The right startup financing option depends on how much money you need, how quickly you need it, your ability to repay it, and how much ownership or control you are willing to give up.
Some entrepreneurs use personal savings and bootstrap their businesses, while others use business loans, equipment financing, crowdfunding, grants, or equity investment. Understanding the differences between these options can help you choose a financing strategy that fits your startup’s stage and financial needs.
Before applying for funding, determine how much capital your startup actually needs and what the money will be used for. A clear funding plan can help you avoid borrowing more than necessary or choosing financing that does not match your business model.
Consider these factors:
Startup costs: Estimate expenses such as registration, technology, equipment, inventory, marketing, professional services, and workspace.
Working capital: Determine how much cash you need to cover ongoing expenses before the business generates consistent revenue.
Repayment capacity: If you are considering debt, estimate whether your expected cash flow can support monthly payments.
Credit history: Personal and business credit can affect the financing products and terms available to you.
Collateral: Some lenders may require assets to secure a loan.
Ownership: Equity financing generally means giving investors an ownership stake in your company.
Growth plans: A business planning for rapid expansion may have different financing needs from a small company focused on steady, self-funded growth.
Funding timeline: Some financing options can take longer to obtain because of applications, underwriting, due diligence, or fundraising.
A simple cash-flow forecast can help you determine how much funding you need and when you will need it.
Startup financing generally falls into two broad categories: debt financing and equity financing. Debt financing involves borrowing money that must generally be repaid, while equity financing involves raising capital in exchange for an ownership interest.
Other funding sources, such as personal savings, crowdfunding, and grants, can have different structures and requirements.
Bootstrapping means financing a business primarily with the founder’s own resources and reinvesting revenue back into the company. Personal savings are one of the most straightforward ways to fund an early-stage business because there is no lender application or outside investor involved.
The main advantage is control. Founders generally do not have to give up equity or answer to outside investors.
However, using personal funds also puts the founder’s own money at risk. Limited capital can also restrict how quickly the business can hire, purchase equipment, market its services, or expand.
Bootstrapping may be appropriate when:
Startup costs are relatively manageable.
The business can begin generating revenue quickly.
The founder wants to retain ownership.
The founder has enough personal capital without creating an unsustainable financial burden.
Business loans provide capital that a startup repays over an agreed period, typically with interest and other applicable costs. Banks, credit unions, and online lenders may offer different business financing products.
Business loans can provide more capital than personal savings, but qualifying can be difficult for a new business with limited operating history. Lenders may consider factors such as credit history, revenue, cash flow, collateral, business plans, and the borrower’s overall financial position.
Before accepting a business loan, review:
Interest rate and total financing cost
Repayment schedule
Loan term
Fees
Collateral requirements
Personal guarantees
Prepayment terms
Whether payments fit your projected cash flow
For a broader look at financing options, see the business financing guide.
Traditional business loans are not the only way to finance a startup. Alternative financing can provide funding for specific needs such as equipment, inventory, or product development.
The right option depends on what you are financing and how the business expects to generate cash.
Equipment financing is designed to help businesses purchase or lease equipment while spreading the cost over time. This can be useful for startups that need expensive machinery, technology, vehicles, or other business equipment to operate.
One potential advantage is that the equipment may serve as collateral for the financing, depending on the financing arrangement and lender.
Equipment financing can make sense when:
The equipment is essential to generating revenue.
The purchase price is too large for the startup’s available cash.
The equipment is expected to remain useful for several years.
Preserving working capital is important.
It is also important to consider maintenance, depreciation, insurance, upgrades, and what happens to the equipment after the financing term ends.
Learn more about the topic in this equipment financing guide.
Inventory financing provides capital that a business can use to purchase inventory before it has enough cash available to pay for it upfront. It can be particularly relevant to retail and e-commerce businesses that need products on hand before sales generate enough cash to replenish inventory.
The key consideration is inventory turnover. If products sell slowly, financing costs can continue while capital remains tied up in unsold inventory.
Before using inventory financing, consider:
How quickly the inventory is expected to sell
Profit margins
Seasonal demand
Storage costs
Financing costs
Expected customer payment timing
You can learn more about the concept in this guide to inventory loans and how they work.
Crowdfunding allows a business to raise relatively small contributions from a large number of people through an online platform. Platforms such as Kickstarter and Indiegogo have been used by businesses and creators to present products and ideas to potential supporters.
Crowdfunding can be useful for startups with a product, concept, or story that can generate interest from a broad audience.
However, successful crowdfunding generally requires more than publishing a campaign. Founders may need to develop a strong presentation, communicate the value of the offering clearly, promote the campaign, and fulfill commitments made to supporters.
Depending on the crowdfunding model, contributors may receive rewards, products, or another form of benefit rather than an ownership stake. Equity-based crowdfunding has different characteristics because investors may receive an ownership interest.
Equity financing involves raising capital by giving investors an ownership interest in the business. Unlike a traditional loan, equity investment generally does not require scheduled principal repayments in the same way debt does, but founders give up some ownership and may have to share future decision-making.
Equity financing can be particularly relevant to startups pursuing substantial growth that may not have enough revenue, collateral, or cash flow to support conventional debt.
Angel investors are individuals who invest their own money in early-stage businesses, typically in exchange for equity or another ownership-related interest.
Some angel investors also bring industry experience, professional connections, or business guidance. However, the relationship involves more than receiving capital. Investors may have expectations regarding business performance, reporting, strategic decisions, and future financing.
Before accepting angel investment, understand:
How much equity is being offered
The company’s valuation
Investor rights
Decision-making arrangements
Future dilution
Reporting expectations
Potential involvement in the business
Venture capital firms invest in startups that they believe have significant growth potential, generally in exchange for equity. VC financing can provide substantial capital and access to networks and expertise, but it is typically associated with businesses pursuing ambitious growth.
Venture capital may not be appropriate for every startup. Founders should consider whether their business model, growth expectations, ownership goals, and long-term plans align with an equity-investment model.
Accepting VC funding can also result in dilution for existing shareholders as additional investment rounds occur.
Government grants can provide funding that generally does not have to be repaid, provided the recipient meets the program’s requirements. Availability, eligibility, application procedures, and funding amounts vary by country, government agency, industry, and program.
Some programs target specific industries, technologies, research activities, geographic areas, or economic-development objectives.
Because grants can be competitive, entrepreneurs should carefully review:
Eligibility requirements
Application deadlines
Eligible expenses
Matching-fund requirements, if applicable
Reporting obligations
Restrictions on how funds can be used
A grant should not be treated as guaranteed startup capital. Build a financing plan that does not depend entirely on receiving a grant unless the funding has already been awarded.
The right financing option depends on your startup’s capital requirements, cash flow, risk tolerance, ownership goals, and stage of development. Instead of choosing financing based only on the amount available, compare the total financial and ownership implications.
| Financing Option | Common Use | Key Consideration |
|---|---|---|
| Personal savings | Initial startup costs | Uses the founder’s own capital |
| Bootstrapping | Early operations and growth | Growth may be limited by available cash |
| Business loans | Working capital and expansion | Requires repayment and may require collateral |
| Equipment financing | Business equipment | Financing is tied to specific equipment |
| Inventory financing | Purchasing inventory | Inventory turnover affects repayment capacity |
| Crowdfunding | Products, projects, or launches | Requires effective promotion and campaign execution |
| Angel investment | Early-stage growth | Requires giving investors an ownership interest |
| Venture capital | High-growth businesses | Can involve significant dilution and investor expectations |
| Government grants | Eligible business activities | Competitive and subject to program requirements |
The best fit also depends on what the money will accomplish. For example, financing a piece of equipment is a different problem from funding several years of rapid expansion.
Startup stage can help narrow the available choices, but there is no universal financing path for every business.
Businesses in the earliest stages may consider:
Personal savings
Bootstrapping
Crowdfunding
Grants
Small business financing, when eligibility requirements can be met
At this stage, keeping fixed financial obligations manageable can be important because revenue may still be unpredictable.
A startup with established revenue and a clearer business model may have additional options, including:
Business loans
Equipment financing
Inventory financing
Angel investment
Other forms of equity financing
The business may also have more financial information available to demonstrate its ability to repay debt or support an investment valuation.
A company with significant growth opportunities may consider larger financing arrangements, including venture capital or other equity investments.
The important consideration is not simply how much capital can be raised. Founders should evaluate how the financing affects ownership, control, cash flow, and long-term business objectives.
Financing decisions can create long-term financial obligations, so avoid choosing funding based solely on how quickly money is available.
Common mistakes include:
Extra capital may sound helpful, but unnecessary debt can increase financing costs and monthly obligations.
Do not focus only on the advertised interest rate. Review fees, repayment terms, collateral requirements, and the overall cost of the financing.
Short-term financing can create cash-flow pressure when used for investments that will take years to generate returns.
Equity can provide valuable capital without traditional loan payments, but selling an ownership stake can affect future control and potential returns.
Startup founders sometimes focus heavily on launch expenses while overlooking recurring costs. Make sure your financing plan accounts for payroll, software, rent, marketing, inventory, utilities, and other operating expenses where applicable.
A financing strategy can include multiple sources. For example, a founder might combine personal capital with equipment financing or use operating revenue to fund future growth.
A well-prepared financing application can make it easier to explain how much money you need and how you intend to use it.
Prepare the following information where applicable:
Business plan: Explain the business model, target market, products or services, and growth strategy.
Startup budget: List one-time and recurring expenses.
Cash-flow projections: Estimate expected revenue and expenses.
Funding request: Clearly state how much capital you are seeking.
Use of funds: Explain exactly how the money will be used.
Financial records: Prepare available personal or business financial information requested by the lender or investor.
Credit information: Understand your credit position before applying for financing.
Repayment or investor strategy: Be prepared to explain how debt will be repaid or how an equity investment supports the company’s growth.
The more clearly you can connect the funding request to a specific business need, the easier it is to evaluate whether the financing makes sense.
There is no single financing method that fits every startup. The appropriate option depends on the amount of capital required, business stage, expected cash flow, credit profile, repayment capacity, and whether the founder is willing to give up equity.
Yes. Personal savings can be used to cover startup costs and allow a founder to maintain ownership. However, founders should carefully consider how much personal capital they can reasonably commit without creating excessive personal financial risk.
They can be. New businesses may have limited revenue history, credit history, or collateral, which can affect eligibility. Lenders may evaluate the owner’s credit, business finances, collateral, cash flow, and other factors.
Equipment financing is used to purchase or lease business equipment while spreading payments over time. It can be useful when a startup needs equipment to operate but wants to preserve some working capital.
Generally, grants do not require repayment when recipients comply with the applicable program requirements. However, eligibility, permitted expenses, reporting requirements, and other conditions vary by grant program.
Debt financing involves borrowing money that generally must be repaid according to agreed terms. Equity financing involves receiving capital in exchange for an ownership interest, which means the founder may give up some ownership or control.
Crowdfunding can be useful for startups with products, concepts, or campaigns that can attract a broad audience. Success depends on the crowdfunding model, campaign execution, audience reach, and the value offered to supporters or investors.
A startup can use multiple financing sources when appropriate. Combining funding methods can help match different expenses with different types of capital, but each source should be evaluated for its cost, obligations, risk, and effect on ownership.
Financing a startup involves more than finding the largest amount of available capital. The goal is to match the financing structure with the business’s actual needs, expected cash flow, growth plans, and ownership objectives.
Personal savings and bootstrapping can help founders maintain control, while business loans can provide capital without giving up ownership. Equipment and inventory financing can address specific operational needs, while crowdfunding, grants, angel investment, and venture capital provide other potential paths.
Before choosing a financing option, calculate your funding requirement, understand the total cost, review the repayment or ownership implications, and make sure the financing supports a realistic business plan.
For entrepreneurs exploring different ways to fund a business, the JNA Financing guide provides another resource for reviewing available financing options.
Conventional Loans: A Complete Guide for Homebuyers
Sep 28, 2026
Holiday Sales Strategies for Telecom Dealers to Grow
Sep 25, 2026
Common Small Business Startup Mistakes to Avoid
Sep 24, 2026
Essential Business Documents for Starting a New Company
Sep 23, 2026
How to Finance Your Startup: A Guide to Funding Options
Sep 22, 2026

9
Sep, 2026
FINANCE
Marketing a franchise successfully requires more than simply promoting a brand. Franchise owners need a...
3
Sep, 2026
FINANCE
Choosing between a personal loan or credit card can be confusing, especially when you need to borrow...
27
Aug, 2026
FINANCE
Small business loans give entrepreneurs access to capital they can use to launch, operate, or...